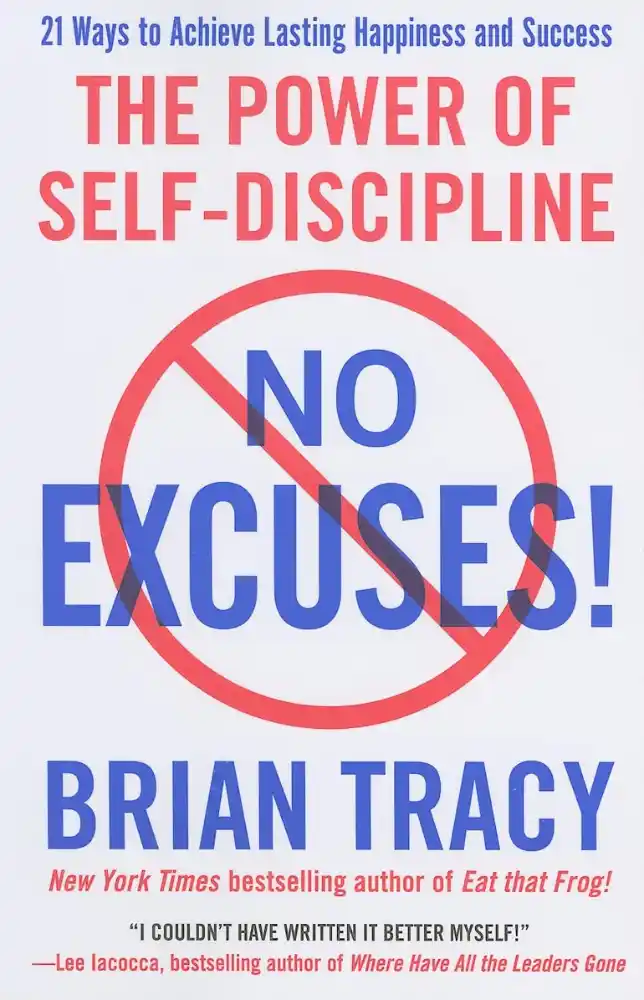
Financial discipline is the habit of saving first, spending deliberately and thinking in years rather than days, and it does more for long-term wealth than a bigger paycheck ever will. Drawing on Brian Tracy’s No Excuses!: The Power of Self-Discipline, this guide shows how self discipline and money fit together, which habits do the real work, and how to put them in place with a simple 90-day plan.
What Is Financial Discipline?
Financial discipline is the consistent practice of managing money according to a plan rather than an impulse: saving before spending, tracking where money goes, avoiding unnecessary debt and investing for the long term. It turns income into lasting security because behavior, not salary, decides what you keep.
Self discipline and money are directly connected, and Brian Tracy makes that connection the heart of his financial advice in No Excuses!. His claim is straightforward: financial success is not primarily about how much you earn, it is about how you behave with what you earn. Plenty of people raise their income and still feel unstable, while others earn moderately and quietly build substantial wealth. The difference is rarely luck. It is disciplined financial behavior sustained over a long period of time.
That idea is worth taking seriously because the numbers back up how fragile many households are. The Federal Reserve’s Survey of Household Economics and Decisionmaking has found that only about 63 percent of U.S. adults could cover a $400 emergency expense with cash or its equivalent, a share that has barely moved in recent years. Income alone does not close that gap. Habits do, and habits are exactly what financial discipline is made of.
Why Financial Discipline Matters More Than Income
It is tempting to believe that more money would solve every money problem. In practice, a higher income without discipline usually produces a higher lifestyle, bigger obligations and the same lack of savings. Discipline is what converts earnings into assets. Without it, a raise simply changes the size of the numbers on the spending side of the ledger.
Financial discipline also works like physical fitness. Nobody becomes strong because of one heroic workout, and nobody becomes wealthy because of one heroic budget. Strength and wealth both come from small actions repeated until they stop feeling like effort. That is why the principles below are deliberately simple. They are not clever tricks. They are behaviors you can sustain for decades, which is precisely what makes them powerful.
Delayed Gratification: The Foundation of Financial Discipline
At the core of self discipline and money lies delayed gratification. Tracy emphasizes that financially successful people consistently choose future security over present indulgence. They save before they spend, they invest before they upgrade their lifestyle, and they make decisions with the long term in mind instead of reacting to how they feel in the moment.
Most financial instability is not caused by low income alone. It is caused by a long chain of impulsive decisions, each one small enough to excuse. Self discipline strengthens the ability to pause before spending and consider the long-term consequences. That pause is the entire skill. You are not trying to eliminate desire; you are trying to put a short gap between the desire and the purchase so that your plan, rather than your mood, makes the final call.
How to Be Disciplined With Money: Pay Yourself First
One of Tracy’s most practical principles is simple: save a portion of every dollar you earn. Not when it is convenient, not when you feel secure, but always. This habit, often called “pay yourself first,” builds financial discipline because it removes the decision from the moment when willpower is weakest. Even a small percentage saved consistently compounds into something significant over decades.
The most reliable way to apply it is to automate it. If your savings are moved out of your checking account on payday, before you have a chance to spend them, saving stops being a daily act of willpower and becomes a system. A few practical ways to set that up:
- Choose a fixed percentage of every paycheck and set up an automatic transfer to a separate savings or investment account on payday.
- Keep that account somewhere slightly inconvenient to access, so that withdrawals require a deliberate decision rather than a tap on your phone.
- Increase the percentage each time your income rises, so your savings rate grows alongside your earnings.
Self discipline and money intersect at exactly this decision to prioritize saving over consumption. Once the transfer is automatic, the discipline has already been done for you.
The Wedge Principle: Why Small, Consistent Investments Win
Tracy describes what he calls the wedge principle. When you consistently save and invest, even modest amounts grow through compound interest. At first, the growth appears painfully slow, which is where most people quit. Over time, it accelerates dramatically, and the later years often produce more growth than the early years combined. The key to the entire process is consistency.
Self discipline ensures the three things compounding depends on: regular contributions, a long-term perspective and resistance to emotional withdrawals. The last one matters more than most people expect. Compounding rewards patience, and patience requires discipline, especially during market downturns or personal emergencies when pulling money out feels sensible. A properly funded emergency account, covered later in this guide, is what protects your long-term investments from being raided every time life gets expensive.
Lifestyle Inflation: The Hidden Threat to Wealth Building
One of the greatest financial traps is lifestyle inflation. Income increases, and expenses quietly increase to match. A better apartment, a nicer car, more dining out and more subscriptions each seem reasonable on their own, but together they absorb the entire raise and leave no progress behind.
Practicing financial discipline means resisting the urge to expand your lifestyle automatically with every pay increase. Instead, keep your living standards modest relative to your income, direct the difference into investments and build reserves. Discipline converts income growth into asset growth, whereas without it, income growth simply becomes expense growth. A useful rule is to split every raise: allow part of it to improve your life now, and send the rest straight to savings and investments before it becomes part of your normal spending.
Financial Responsibility and Control: Track, Budget, Review
Tracy connects financial success to responsibility. Blaming the economy, your employer or your circumstances might feel justified, but it weakens your sense of agency. Taking responsibility strengthens control, and control increases confidence. Financial clarity reduces anxiety, and responsibility creates leverage because it gives you something concrete to change. If you want a deeper look at this mindset, our guide on self discipline and personal responsibility explains why ownership comes before progress.
In practical terms, responsibility means building a simple system for knowing where your money goes. That system has three parts.
Track Your Spending
You cannot manage what you cannot see. For at least 30 days, record every expense in a spreadsheet, a notebook or a budgeting app, and sort it into categories such as housing, food, transport, subscriptions and entertainment. Most people are surprised by what they find, particularly by small recurring charges they have stopped noticing.
Build a Budget That Fits Real Life
A budget is simply a plan for where your money should go before the month begins. The best budgets are realistic rather than punishing. Many people abandon budgeting not because they are bad with money but because their budget was built on idealistic assumptions. Include a small amount of fun money that you can spend however you like, so the plan feels sustainable instead of restrictive. A budget that you can follow for years will always beat a perfect one that you abandon after three weeks.
Hold a Weekly Money Review
Set aside 15 to 20 minutes each week to check your accounts, compare your spending to your plan and look ahead at upcoming bills. Some people call this a weekly money date. The name does not matter, but the rhythm does. A short, regular review catches small problems before they become large ones and keeps your finances in the front of your mind without taking over your life.
Build an Emergency Fund to Protect Your Financial Discipline
An emergency fund is the safety net that lets the rest of your plan survive real life. Without one, a car repair or medical bill goes onto a credit card, and the debt it creates undermines every other good habit you have built. Most financial educators suggest working toward three to six months of essential living expenses, but you do not need to start there. A first target of one month, or even a few hundred dollars, already changes how you handle the unexpected.
Keep the fund in a separate, easily accessible account that is not tied to your daily spending, and treat it as untouchable except for genuine emergencies. A sale is not an emergency. A broken water heater is. The distinction between a need and a want is one of the quiet skills that financial discipline trains, and an emergency fund gives you daily practice at it.
Avoiding Debt Traps
Tracy warns about unnecessary debt. While certain strategic investments may make sense, consumer debt often undermines financial progress because it commits future income to past spending, usually at a high interest rate. Debt very often reflects emotional spending patterns, and the cure is not a clever product but a change in behavior.
Financial discipline in practice means avoiding impulse credit use, paying balances on time and in full whenever possible, and limiting your financial obligations to what you can comfortably carry. If you already carry balances, make a list of every debt with its interest rate and balance, then choose a payoff method you will actually stick with. Some people prefer to clear the smallest balance first for momentum, while others target the highest interest rate to save the most money. Either approach works if you follow it consistently. Discipline replaces the old, reactive patterns with intentional planning.
Investing in Earning Ability
Tracy emphasizes that your most valuable financial asset is your ability to earn. Self discipline and money growth are therefore connected through skill development, not just saving. Putting time and money into education, training, professional growth and networking increases your long-term income potential, and a higher income combined with disciplined habits is the fastest route to meaningful wealth.
Financial discipline is not only about saving. It is also about expanding your earning capacity so that the money you save has more to work with. If you are looking for strategies that go beyond the basics, our guide on how to create wealth as a man covers the broader picture of building income and assets over time.
The Emotional Side of Money: How to Stop Impulse Spending
Money is rarely purely logical. Emotions influence spending decisions far more than most people admit, and they tend to show up in three forms: stress spending, status spending and impulse buying. Each one feels like a solution in the moment and a mistake a week later.
Self discipline creates a space between emotion and action, and you can make that space more reliable with a few simple tools. The first is the 24-hour rule, a technique popularized by money educators such as Rachel Cruze: for any unplanned purchase above a set amount, wait a full day before buying. Many wants fade overnight. The second is a short list of questions to ask before you pay:
- Does this purchase align with my long-term goals?
- Is this necessary, or is it emotional?
- What is the opportunity cost of spending this money instead of investing it?
Financial maturity grows when discipline governs decisions rather than impulse. The aim is not to feel nothing when you want something. It is to notice the feeling, name it and then decide on purpose.
Long-Term Wealth Thinking
Short-term thinking leads to debt, and long-term thinking leads to wealth. Tracy consistently emphasizes thinking years ahead, and the questions he encourages are useful at any income level:
- Where do I want to be financially in ten years?
- What habits must I establish now to get there?
- What financial behaviors must I eliminate?
Self discipline and money stability grow through a sustained long-term vision, because a vision gives each small sacrifice a purpose. Saving feels very different when it is attached to something you actually want, such as a home, a business, a period of freedom or the ability to support your family. Write your goals down, attach a rough number and date to each, and review them at least twice a year. If you want to measure progress across more than just your bank balance, Sahil Bloom’s framework in the Wealth Score is a helpful companion.
The Benefits of Financial Discipline: Freedom and Peace of Mind
Financial freedom is not extravagance. It is flexibility: the ability to make decisions without financial desperation. Self discipline and money habits create options, including career flexibility, reduced stress, greater security and increased generosity. Freedom grows gradually through disciplined saving and investing, rarely in a dramatic leap.
There is also a psychological payoff that is easy to underestimate. When your finances are stable, stress decreases, decision-making improves, confidence increases and relationships strengthen. Financial clarity creates emotional stability, while financial chaos creates tension that spills into every other part of life. Self discipline and money management, practiced together, improve mental well-being as well as net worth.
Common Financial Discipline Mistakes (and How to Recover)
Almost everyone slips at some point, and how you respond to a slip matters more than the slip itself. These are the mistakes that most often derail people, along with the simple fix for each.
- Aiming for perfection. Discipline is not about being perfect with money. If you overspend one month, adjust the next month’s plan and carry on rather than abandoning the whole system.
- Setting a budget that is too strict. A plan with no room for enjoyment will eventually be broken. Build in fun money from the start.
- Saving without a plan. Putting money aside is good, but financial discipline also means managing spending, debt and goals. Savings alone do not make you disciplined if the money is spent again on impulse.
- Keeping everything in your head. Money you do not track is money you cannot control. Write it down.
- Going it alone. Talking about your goals with a trusted friend, partner or financial professional adds accountability and makes the habits easier to keep.
If you want to strengthen the underlying skill of consistency, our guide on self discipline and time management shows how the same principles apply to your hours as well as your dollars.
A 90-Day Financial Discipline Plan
To strengthen self discipline and money habits, work through the following steps in order. Each one builds on the last, and the whole sequence takes roughly three months.
- Days 1 to 30: Track everything. Record every expense for 30 days without judging it. The goal is awareness, not change.
- Set a fixed savings percentage. Choose a number you can sustain, even if it is small, and commit to it as a non-negotiable.
- Automate your savings. Schedule the transfer for payday so that saving happens before spending.
- Review your investments monthly. Check contributions and progress, but resist the urge to react to short-term market movements.
- Identify one expense category to reduce. Pick the area that surprised you most during tracking and cut it by an amount you will not miss.
- Start or grow your emergency fund. Direct a portion of your savings to a separate account until you reach your first target.
After 90 days, patterns become clear, financial confidence increases and discipline becomes routine. At that point, increase your savings rate by one or two percentage points and repeat the cycle. If you would like a broader framework for building these habits into every area of your life, the free mini course on discipline linked at the end of this article is a good next step.
Frequently Asked Questions About Financial Discipline
What is financial discipline?
Financial discipline is the consistent practice of making money decisions according to a plan instead of an impulse. It includes saving regularly, tracking spending, avoiding unnecessary debt and investing for the long term.
How are self discipline and money connected?
Financial stability results from disciplined saving, spending and investing habits sustained over time. Self discipline is the skill that lets you follow your financial plan when your emotions or circumstances push you to abandon it.
How do I become disciplined with money?
Start by saving a fixed percentage of every paycheck and automating the transfer. Then track your spending, build a realistic budget with some room for fun money, and review your numbers weekly. Small, repeated habits build discipline faster than dramatic changes.
Is a high income necessary to build wealth?
No. Consistent saving and investing matter more than income alone. People with moderate incomes who save steadily and avoid lifestyle inflation often build more wealth than high earners who spend everything they make.
What is the wedge principle?
The wedge principle, as Brian Tracy describes it, explains how small, consistent investments grow significantly over time through compound interest. Growth looks slow at first and accelerates later, which is why consistency matters more than the size of any single contribution.
Why do so many people struggle with money?
Spending is often emotional rather than strategic. Stress, status and impulse purchases override long-term goals, especially when there is no budget, no emergency fund and no automatic saving system to protect the plan.
Can financial discipline be learned?
Yes. Like any skill, it improves with practice. Start small, stay consistent and adjust when you slip. Most people find that the habits feel difficult for the first month and increasingly natural afterward.
Final Reflection: Financial Discipline Is a Long-Term Habit
Financial discipline is the quiet engine behind lasting wealth: save regularly, spend carefully, invest wisely, think long term and take responsibility for your decisions. In No Excuses!, Brian Tracy presents a simple but demanding message, and over time that discipline turns ordinary income into extraordinary stability.
Take the FULL FREE MINI COURSE on DISCIPLINE here
Related posts:
 Get Smart by Brian Tracy: The Complete Summary Guide to Thinking Like Successful People
 Why Slow Thinking Beats Fast Reactions in High-Stakes Decisions
 Self Discipline and Success: Why Winners Refuse Excuses
 Why Only 3% of People Write Down Goals—and How This Quietly Creates the Wealth Gap
 Why Long-Term Thinking Determines Wealth (More Than Talent or Income)