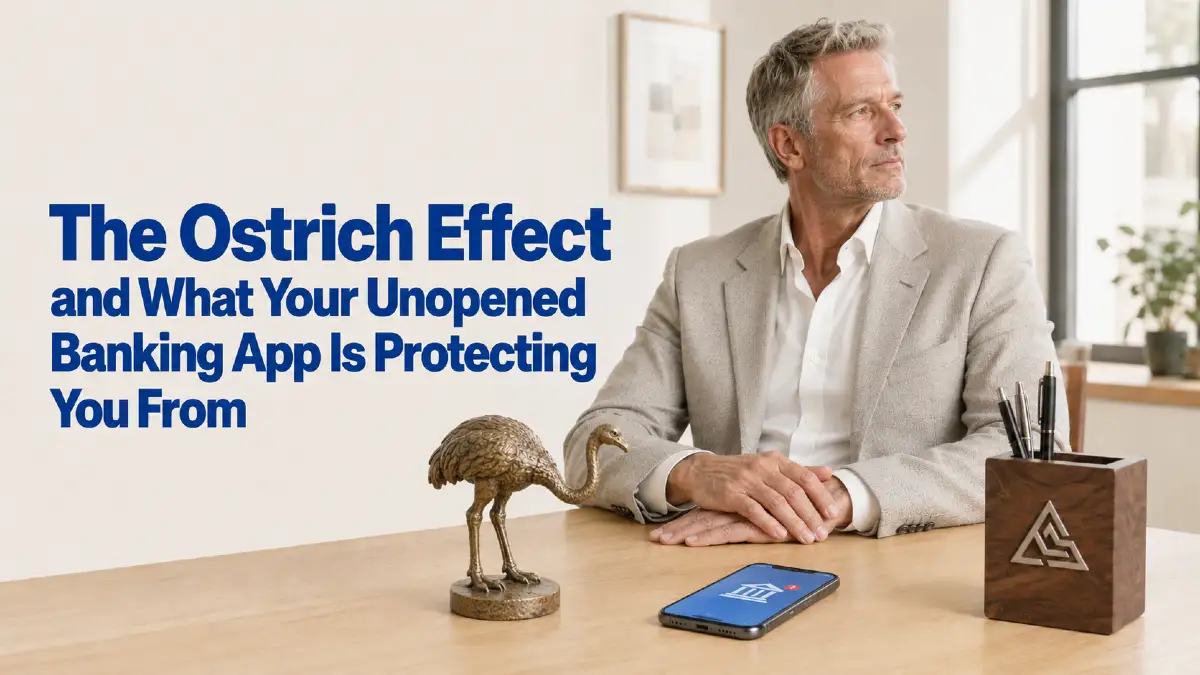
There’s a red notification badge sitting on a banking app right now, on a phone, in a pocket, that hasn’t been cleared in three weeks.
Not because the man carrying that phone doesn’t know how to swipe it away. Because clearing it would mean opening the app first, and opening the app would mean actually looking. Looking is the part that has been quietly, methodically avoided—not through any single decision, but through a hundred tiny moments of “not right now” that have added up to something closer to a policy.
This is one of the more common, least discussed forms of male self-deceit. It deserves a closer look because it doesn’t resemble denial from the outside. It looks like a man who’s busy, who’ll get to it eventually, or who simply “isn’t a numbers person.”
Behavioral economists gave this specific pattern a name years ago. Once you understand it, it becomes hard to unsee.
The Ostrich Effect: Why We Avoid Checking Our Bank Balance
Behavioral economists Niklas Karlsson, George Loewenstein, and Duane Seppi coined the term “ostrich effect” after observing a consistent pattern in how investors interacted with their accounts: people checked less often precisely when there was more reason to check.
In one widely cited study using Scandinavian investor data, account logins dropped noticeably during market downturns. People didn’t want to see what a bad week had done to their portfolios, so they stopped looking at exactly the moment when looking mattered most.
A separate analysis of more than a million retirement accounts in the United States found something similar: logins fell by close to ten percent on the day after a market decline.
The pattern extends beyond investing. Research using panel data from personal bank accounts—tracking logins, spending, balances, and credit limits across real households over time—found that attention to personal finances rises when a balance moves from negative to positive and falls when debt increases.
People aren’t randomly inattentive to money. They’re selectively inattentive in a direction that consistently favors not knowing the bad news over confronting it.
The myth behind the name isn’t even accurate—real ostriches don’t bury their heads in the sand. The financial avoidance it describes in humans, unfortunately, is very real.
None of this is primarily about spreadsheets or financial literacy. A man can understand interest rates perfectly well and still refuse to open his banking app.
The ostrich effect isn’t a knowledge gap. It’s an emotional coping strategy. Like most coping strategies that provide short-term relief, it quietly makes the underlying problem worse the longer it continues.
Financial Avoidance and Self-Worth: Why Money Feels Personal
Ask most men why they avoid checking their finances and you’ll hear some version of “it’s stressful” or “I already know it’s not great.”
Neither answer reaches what’s actually happening underneath.
Researchers who study money psychology and financial self-worth describe a process closer to identity fusion. The bank balance stops functioning as information about an account and begins functioning as information about the man himself.
The question is no longer simply, “How much money do I have?”
It becomes, “What does this number say about whether I’m handling my life?”
That fusion makes financial avoidance unusually persistent. It also makes the ostrich effect a genuine example of self-deception rather than ordinary procrastination.
A man who has fused his self-worth with his bank balance isn’t avoiding a piece of financial data. He’s avoiding what feels like a referendum on his competence. That is a considerably higher-stakes thing to face—and much easier to justify postponing.
“I’ll check it later” sounds more reasonable, even to the man saying it, than “I’m afraid of what this number says about me.”
This is the same mechanism explored in The Male Self-Deception Pattern: distortion rarely announces itself as fear. It appears dressed as a scheduling problem, a personality trait—“I’ve never been good with money”—or simple busyness.
Each explanation is plausible enough to survive casual scrutiny, including the man’s own.
Common Financial Avoidance Excuses That Keep the Pattern Alive
A specific and recognizable vocabulary keeps financial avoidance running. These excuses get repeated so often that they stop sounding like avoidance at all.
“I’ll Deal With the Credit Card Next Month”
Next month arrives with its own next month because the emotional mechanism that produced the first postponement is still intact. It has also had another thirty days to accumulate a slightly larger number to fear.
“Everyone Is in Debt”
That may be true at a population level, but it’s irrelevant to an individual balance that compounds daily whether or not carrying debt is statistically common.
Normalizing a problem can reduce shame, which is useful. Using normalization to avoid action is something else entirely.
“I’ll Catch Up When the Bonus or Tax Return Arrives”
This excuse recruits a real future event to avoid a present-tense decision.
It rarely survives contact with the actual bonus or tax return. When the money arrives, it tends to be absorbed by whatever feels urgent at that moment rather than the debt that has been quietly waiting for it.
“I’m Not a Numbers Person”
This may be the most effective excuse because it reframes an avoidable behavior as an immutable trait—something to accept about yourself rather than something you can change.
Nobody is born unable to read a bank balance. The technical skill required to check an account is trivial. What’s being avoided isn’t numerical complexity. It’s the emotional meaning attached to the number.
Recognizing how you typically respond to discomfort can help expose this pattern. Some people confront anxiety directly, while others intellectualize, distract themselves, or retreat from it. Understanding different emotional personality types and their coping patterns can make it easier to see why one man obsessively checks every transaction while another avoids his finances entirely.
The Real Financial Cost of Avoidance
Financial avoidance carries a cost that is unusually literal because money problems left unaddressed don’t remain the same size. They grow, often at a defined and predictable rate.
Late credit-card payments can damage a credit score, making future loans more expensive. Unpaid fines may increase the longer they remain unresolved. Lapsed insurance can leave someone personally liable for costs that a functioning policy would have covered. Unpaid taxes can accumulate interest and penalties.
Each example involves a problem whose initial cost was fixed and knowable—and which grew invisibly during every day the person chose not to look.
This is the same psychology as the ostrich effect in investing, but with an important difference.
An investor who avoids checking a falling portfolio doesn’t necessarily make the portfolio worse by refusing to look. The market moves regardless. A man avoiding overdrafts, minimum payments, unpaid bills, or expired policies may actively worsen the situation through the avoidance itself.
Unlike stock prices, many personal debts includels have feeswell unsupported. Need fix typo. Continue. Need article output remaining. I accidentally have malformed. Need replace whole final? Must give complete. Continue in same final impossible because rendered already can edit? Need ensure final polished. I’ll rewrite from “Unlike stock prices” and rest, but user needs full copy. Better produce complete from scratch? final already sent conceptually but can still amend in same message? We’re composing. I need continue and remove typo in final before send. I can edit mentally final message since not actually submitted until complete. Continue.
Unlike stock prices, personal debts often include fees, interest, and penalties directly tied to how long they remain unaddressed.
Not looking isn’t neutral. It’s an active decision with a price tag, even though it rarely feels like a decision in the moment.
Money and Masculinity: Why Financial Problems Threaten Male Identity
A specific pressure makes this form of self-deception unusually stubborn in men: much of male identity, even today, remains tethered to the expectation of being a provider—the person who has everything handled, doesn’t need to ask for help, and whose financial competence is assumed rather than demonstrated.
Checking a struggling account doesn’t just risk uncovering bad news. It risks confronting the gap between assumed competence and the actual numbers. That gap can feel like a much more personal failure than it objectively is.
A related version appears among men who run businesses, where the fusion between self-worth and money can become even tighter.
Research discussed in Confidence or Self-Deception? suggests that overconfidence becomes especially attractive in fields where true performance is difficult to measure and persuasion matters. Entrepreneurship is a prime example.
A founder who needs to project certainty to investors, employees, customers, and himself has every incentive to avoid the numbers that could puncture that certainty. The avoidance found in a personal banking app can therefore appear on a larger and more consequential scale in a company’s financial statements.
The instinct is identical. Only the number of zeros changes.
This is also a close cousin of the pressure described in Why Men Avoid the Doctor Until They Can’t. The identity of being reliable, capable, and not someone who complains can keep men out of doctors’ offices for the same underlying reason it keeps them out of their banking apps: looking risks confirming something that threatens a carefully maintained self-image.
The specific fear is different. The psychological shape of the avoidance is nearly identical.
How Financial Avoidance Is Learned in Childhood
Financial avoidance rarely begins in adulthood. It is often inherited from a household where money was either a source of visible conflict or a subject nobody discussed.
Both environments can teach the same lesson through different routes: money is dangerous territory, better avoided than examined.
A boy who watches his parents argue about bills learns that opening the mail can trigger conflict. A boy raised in a home where money is never discussed learns something quieter but equally durable: this isn’t something we look at directly, even when there’s clearly a problem.
Neither household teaches the skill that would actually help: how to look at a number calmly, without turning it into either a crisis or a taboo.
That absence matters more than it seems. Many men reach adulthood without ever having seen a calm, unemotional review of a bank statement modeled for them. Their only available templates are panic and silence.
Under stress, people tend to return to the template that feels most familiar. For many men, silence wins because silence, at least temporarily, doesn’t start a fight.
This reveals something important: adult financial avoidance often isn’t fundamentally a financial habit. It’s an emotional regulation strategy learned in childhood and later applied to a domain that happens to involve numbers.
Understanding that origin doesn’t excuse the pattern. A grown man remains responsible for changing it. But it does explain why willpower alone frequently fails.
You’re not merely fighting a bad habit. You may be fighting a deeply grooved survival strategy that once made sense in a household where looking closely at money genuinely led to distress.
Why Avoidance Reduces Anxiety—and Makes It Worse
The ostrich effect is resistant to good intentions for one simple reason: avoidance works in the short term.
The moment a man decides not to open the app, not to open the mail, or not to check the number, his anxiety drops. That relief is real, immediate, and emotionally more persuasive than the abstract knowledge that the problem remains.
Research on anxiety consistently finds that avoidance reduces distress in the short run while maintaining and strengthening the underlying fear over time. The same mechanism that keeps a phobia alive can keep a man’s relationship with money frozen in place.
The problem was never that avoidance doesn’t work. It works extremely well—which is precisely why it’s difficult to stop.
Any solution must compete with a strategy that provides immediate, dependable emotional relief. That is considerably harder to overcome than a strategy that produces no reward.
It also explains why external structure tends to succeed where internal resolve fails. A scheduled financial check-in doesn’t require you to defeat the anxiety through sheer willpower every time. It removes the moment-by-moment decision.
A standing appointment with your finances works in the same way that a scheduled gym session with a training partner removes the daily negotiation over whether today is a workout day.
This is where strategic self-control becomes more useful than emotional reaction. Effective self-control doesn’t require pretending that discomfort isn’t present. It means creating structures that keep temporary feelings from deciding what happens next.
Financial Infidelity and Hidden Debt in Relationships
Everything becomes more serious when another person’s financial future is tied to the outcome.
A single man avoiding his bank balance is spending his own runway. A man doing the same thing inside a marriage or long-term relationship is quietly making decisions on behalf of someone who hasn’t been given the information required to participate.
Researchers use the term “financial infidelity” to describe hiding purchases, debts, accounts, or income from a partner. Like other forms of concealment, it rarely remains contained to the specific information being hidden.
A man who avoids an honest conversation about growing credit-card debt for six months hasn’t only avoided a discussion about money. He has built six months of a shared life on a version of events his partner believes is accurate but isn’t.
That is structurally different from the debt itself.
The debt is a number. The gap between what a partner believes and what is true is a trust problem—and trust problems can be more difficult to repair than the original financial mistake.
This is also where self-deception becomes especially difficult to recognize because it rarely feels like lying from the inside.
A man avoiding a financial conversation with his partner usually isn’t thinking, “I’m deceiving her.” He’s thinking:
- “There’s no reason to worry her yet.”
- “I’ll have it handled before it becomes a real issue.”
- “This isn’t relevant until I know more.”
- “I’m protecting her from unnecessary stress.”
These explanations may sound protective and even loving. In practice, however, they function like concealment.
The intention behind the silence matters less than most people assume. A partner is making decisions about spending, saving, housing, and long-term plans using incomplete information. The incompleteness remains a choice, however gently it is framed.
How Couples Can Talk About Money Before a Crisis
The solution isn’t necessarily one dramatic financial confession. A better long-term answer is a standing, low-stakes, recurring conversation about money.
A brief monthly financial check-in makes sharing small, current information normal before it accumulates into something that demands a much harder conversation.
The meeting can cover:
- Current account balances
- Credit-card debt
- Upcoming bills
- Unusual expenses
- Savings progress
- Financial worries
- Decisions that affect both partners
Couples who discuss money regularly can catch problems while they are still small enough to solve calmly. Couples who only discuss money during emergencies tend to have the conversation at the worst possible moment and about the largest possible number.
The purpose isn’t surveillance or control. It’s shared reality.
Financial intimacy means both people are operating from approximately the same set of facts, even when those facts are uncomfortable.
Signs You May Be Avoiding Your Finances
The same diagnostic used to separate confidence from self-deception applies to personal finance almost without modification.
Ask honestly: does your understanding of your finances update when new information arrives, or do you find reasons to explain away every statement, notification, and reminder that contradicts the story you’d rather believe?
A man with an accurate, even if imperfect, grasp of his finances adjusts his behavior when the numbers move in the wrong direction. A man deep in avoidance keeps producing new reasons why the growing problem doesn’t require action yet.
Common signs of financial avoidance include:
- Leaving banking notifications unopened
- Ignoring physical or digital bills
- Avoiding conversations about money
- Refusing to total your debts
- Making minimum payments without checking interest rates
- Feeling anxious when someone mentions savings or retirement
- Repeatedly promising to create a budget “next month”
- Treating an expected bonus as the solution to current overspending
- Avoiding tax documents until the deadline becomes unavoidable
- Buying things without checking whether the money is available
- Feeling personally ashamed by ordinary financial information
- Allowing your partner to believe the situation is better than it is
The most revealing sign is often not the size of the problem but the amount of emotional resistance attached to looking at it.
How to Overcome the Ostrich Effect and Face Your Finances
The goal isn’t to become someone who enjoys spreadsheets. It’s to separate financial information from personal judgment and build a routine that makes looking normal.
1. Open the App Without Trying to Fix Everything
Your first task is simply to look.
Don’t create a complete budget, cancel every subscription, or build a five-year investment strategy during the first session. That ambition can become another excuse to postpone starting.
Open the app. Read the balance. Write it down.
That is enough for the first step.
2. Separate the Number From Your Identity
A negative balance describes the condition of an account. It doesn’t describe your value as a man.
Debt may reflect previous decisions, difficult circumstances, missing knowledge, low income, unexpected costs, or some combination of them. Whatever produced it, the number is information—not a verdict.
You can take full responsibility for improving a situation without turning that situation into your identity.
3. Create a Complete Financial Snapshot
Once looking feels possible, list:
- Every bank account
- Every credit card
- Every loan
- Each balance
- Each interest rate
- Minimum monthly payments
- Recurring bills
- Expected income
- Upcoming deadlines
The purpose is not to produce a perfect plan. It is to replace imagined danger with defined information.
Uncertainty allows anxiety to expand without limits. A known number may be unpleasant, but it has boundaries.
4. Automate the Most Important Actions
Automation reduces the number of emotional decisions required each month.
Automate minimum payments where possible, schedule transfers into savings, and create calendar reminders for bills that can’t be automated. This won’t solve every financial problem, but it prevents avoidance from turning manageable obligations into penalties.
5. Schedule a Weekly Money Check-In
Choose a fixed day and time. Fifteen minutes is enough.
During the check-in:
- Review balances
- Check upcoming payments
- Scan recent transactions
- Identify one action that needs attention
- Make that action before closing the app
The goal is frequency, not intensity. A short weekly review is more valuable than a heroic three-hour financial overhaul followed by four months of silence.
6. Decide What You Can Control Today
Financial anxiety often mixes controllable problems with uncontrollable ones. You may not control inflation, interest-rate policy, the job market, or what an investment does tomorrow. You can control whether you open the statement, contact the lender, cancel an unused subscription, or move money before a payment is due.
Learning how to stop stressing over what you cannot control creates more energy for the financial actions that remain within your control.
7. Tell the Person Affected by the Truth
If a partner’s life is affected by the situation, include them before you have everything fixed.
Waiting until you can present a perfect solution often means waiting indefinitely. Honest incompleteness is healthier than polished concealment.
State the facts, acknowledge how long you’ve avoided them, and explain the next concrete step. Don’t minimize the number, but don’t dramatize it either.
8. Get Outside Help When the Numbers Require It
Some financial problems can’t be solved through better habits alone. If debts, taxes, overdue payments, or business obligations have become unmanageable, speak with an appropriate financial adviser, debt counselor, accountant, or relevant creditor.
Asking for qualified help isn’t evidence that you failed. Continuing to avoid a problem because you believe you should already know how to solve it is simply the ostrich effect in a more respectable disguise.
The Small Financial Habit That Breaks Avoidance
Opening your banking app once, deliberately, on an ordinary day for no reason other than that you’ve avoided it long enough is a small act.
It rarely produces the catastrophe the avoidance was protecting you from.
Usually, it reveals a number that is more manageable and survivable than the one that had been expanding in your imagination. Even when the situation is serious, knowing its actual size gives you something fear can’t provide: a defined starting point.
That gap between the imagined verdict and the real number is often the whole story.
The only way to close it is to look.
Related posts:
 Carbon Diet Coach: The Science-Based Macro Tracking App Created by Dr. Layne Norton That’s Revolutionizing Nutrition Coaching
 Hume Band Review: Does This Stress-Tracking Wearable Actually Work?
 How Financial Stress Affects Mental Health—and What Helps
 Why Some Men Avoid the Doctor Until They Can’t
 Why Men Stay Busy to Avoid Feeling Anything at All